
Last updated on November 5th, 2026 at 05:50 pm
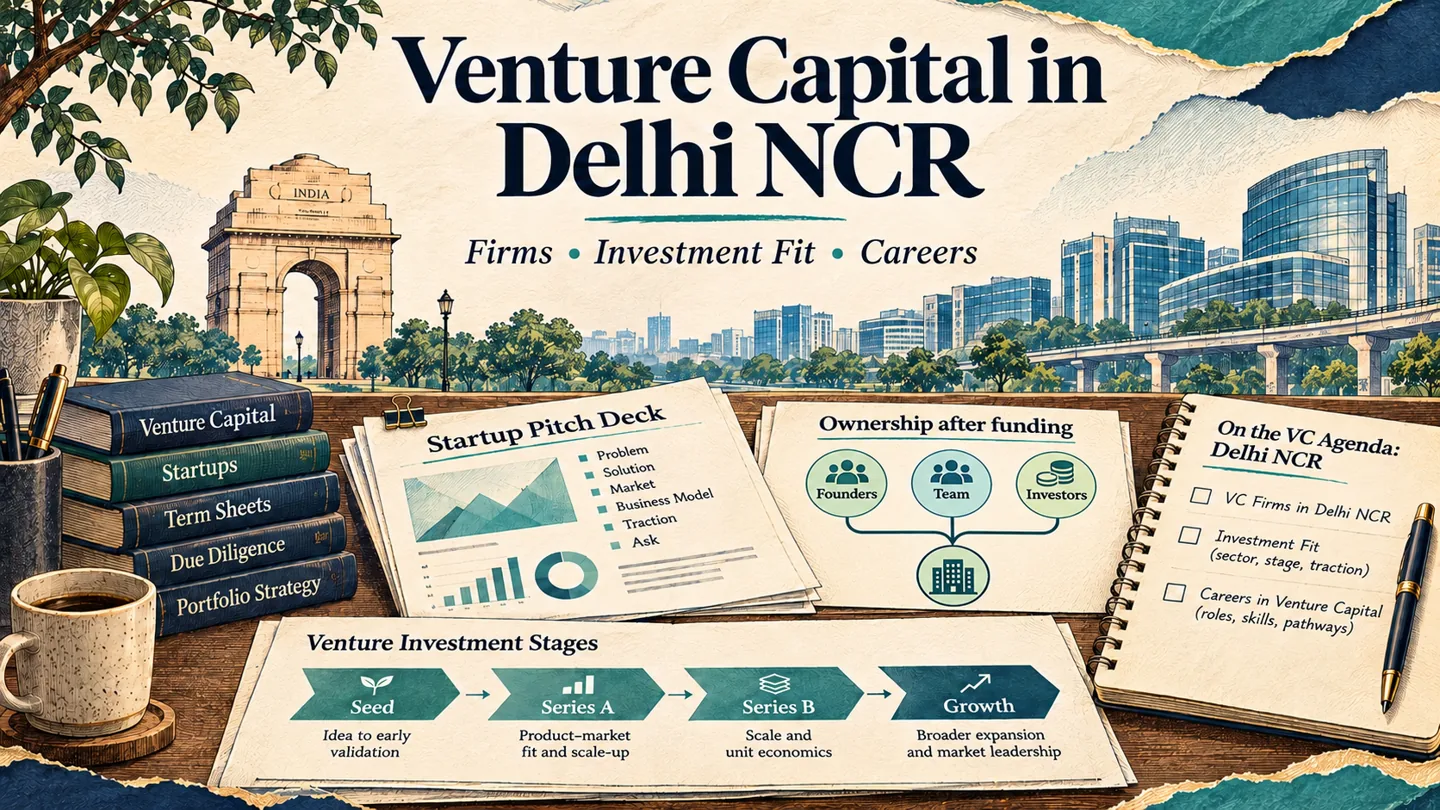
Venture capital firms in Delhi are not one interchangeable group. Some manage funds, some organise angel investments, and some operate internationally with Delhi-based team members. For a founder, the useful question is whether the investor fits the business and funding stage. For a job seeker, it is what the team actually does and what evidence of ability you can bring.
This guide reviews five organisations using their official team, portfolio and contact pages, checked 5 November 2026. It separates New Delhi from Gurugram and a Delhi team presence from headquarters. It is a research shortlist, not a ranking by returns, reputation or likelihood of funding. No listing implies an open vacancy, an active cheque-writing mandate or an invitation to invest in a fund.
Venture capital firms in Delhi NCR: a verified starting shortlist
| Organisation | Location evidence | What the official material establishes | Useful next step |
|---|---|---|---|
| She Capital / SC Founders Fund | Team page publishes a New Delhi address in SDA Market. | Named investment leadership and separate named fund/manager entities. | Read the team and portfolio, then verify the current mandate for the relevant fund. |
| Titan Capital | Official portfolio/team pages give M3 M Urbana, Sector 67, Gurugram. | Separate seed and early-growth investment teams and portfolio examples. | Research the relevant team and company stage; Gurugram is NCR, not New Delhi. |
| Leo Capital | Official site names Delhi among its hubs; team page lists Delhi-linked personnel. | A cross-continental early-stage investor, with Singapore/Helsinki positioning. | Use the team and portfolio to establish fit; do not label it a Delhi-headquartered firm. |
| growX | Retained as a research lead; reviewed contact page does not establish a current Delhi street office. | Official history describes an enterprise/deep-tech orientation and fund entities. | Verify current office geography before relying on a local-directory label. |
| Indian Angel Network / IAN ecosystem | Delhi connection documented in an Indian government incubator listing; confirm current operating contact separately. | An angel-network route and a portfolio spanning several sectors; do not equate every activity with one VC fund. | Identify the exact network or fund route and current contact before pitching or applying. |
1. She Capital: research the fund identity as well as the brand
She Capital’s official team page names Anisha Singh as founder and Arjun Basu as managing partner, and publishes a New Delhi address. It also identifies She Capital Fund and SC Founders Fund separately, with different manager entities. That distinction is useful: a brand name is not a substitute for identifying the fund that would make a proposed investment.
Its portfolio page gives concrete companies and founders to research. Rather than repeating the brand’s positioning as a slogan, choose two relevant companies and ask what their products, customers and economics have in common. That is how you begin to test fit. A historical portfolio relationship does not prove the investor is seeking the same kind of company today.
For founders: establish the current fund’s mandate and explain why your company fits it. Do not assume that every fund under the same brand has identical criteria. For candidates: prepare a short market map around a relevant portfolio theme, with your sources and unresolved questions. A useful research note demonstrates thought; a list of famous founders does not.
For a concrete comparison, the portfolio page describes ellementry as a home-and-lifestyle business and BrainSightAI as a medical-technology business. Those companies require different research: distribution and inventory for the former, clinical use and product evidence for the latter. These are our analytical questions, not undisclosed investment criteria from She Capital. The examples show why a portfolio should be studied company by company.
2. Titan Capital: distinguish seed, early growth and corporate functions
Titan Capital’s official team directory separates seed investment, early-growth investment and corporate functions. It names technology and consumer investment roles and provides a Gurugram address. This makes it a clear NCR inclusion, while also showing why “venture capital job” is too broad a target: investment analysis, fund finance and community work are different functions.
The official site presents portfolio relationships including Razorpay, Urban Company, OfBusiness and Credgenics. These examples span distinct business models. A founder should examine the relevant investment route, while a candidate can compare what matters in payments infrastructure, a services marketplace or collections software. Do not infer a current investment ticket or available capital from the prominence of past companies.
Our research assessment: the published team structure is especially useful for making a focused approach. An application that says “I want a finance job” leaves the reader to do the matching. A note explaining which sector you have researched, the question you investigated and the evidence you found is easier to evaluate. Team membership does not establish that the team is hiring.
3. Leo Capital: a Delhi connection within an international organisation
Leo Capital’s official site describes cross-continental early-stage investing and names Delhi among its hubs. Its team directory lists Rajul Garg with a Delhi/Philadelphia connection and also identifies Delhi-linked finance and platform personnel. That supports a Delhi connection; it does not support calling the entire firm Delhi-headquartered.
For a founder, the relevant research question is how the company’s market and operating geography fit the investor’s stated approach. For a candidate, ask whether a role belongs to investments, portfolio support or finance, and where the work is actually based. Remote collaboration and a city on a biography do not prove a local vacancy.
Research task: select one company from the official portfolio, identify its customer and source of revenue, and write down the cross-border challenge it faces. Separate your analysis from facts confirmed by the company. For example, “customer acquisition may become expensive” is a hypothesis; a disclosed acquisition-cost figure with a date is evidence. An analyst needs both, clearly labelled.
Leo’s homepage also names Dezy and HealthAssure among its portfolio relationships. Both sit around healthcare, but a dental-care business and a healthcare-access platform should not be modelled as the same business. An analyst would separate who pays, how service delivery works and how revenue becomes cash. The portfolio labels establish the relationship presented by the investor; they do not disclose current valuations or investment returns.
4. growX: enterprise and deep-tech research, with location still to confirm
The growX history page describes its evolution from angel activity toward enterprise and deep-tech investing. It names Quandl as an early investment and identifies its regulated fund entities. The contact page separates funding and careers enquiries. These are useful primary sources for understanding the organisation, but the reviewed contact page did not establish a current Delhi street address.
We therefore retain growX as a lead to verify rather than silently treating old directory geography as current fact. This matters if the purpose is to find local employers or arrange an office visit. Confirm the current office and role location through the official route. Do not travel based on this entry.
For technical-company research: an enterprise or deep-tech proposition may require more than a consumer-style download chart. Investigate the buyer, development cycle, procurement hurdles, evidence that the product works and the capital required before meaningful sales. These are analytical questions, not a claim that every growX investment follows one checklist.
There is a concrete historical example behind growX’s enterprise orientation: its own timeline identifies Quandl as an early investment and records its acquisition by Nasdaq. The same timeline describes the later development of deep-tech investing. This is evidence about the firm’s stated history, not proof of the realised return or its current fund’s performance. A candidate researching the firm could compare the commercialisation of a data business with that of a hardware or engineering venture, identifying the different time and capital constraints.
5. Indian Angel Network: do not confuse the network with a single fund
The official IAN portfolio covers a broad range of sectors. Its own disclaimer describes IANPL as facilitating introductions between investors and startups. A government incubator listing documents a New Delhi connection. Neither fact means that every investment is made by the same legal vehicle or under one mandate.
For a founder, identify the appropriate current network or fund channel. For a candidate, establish which organisation would employ you and whether the work is investment research, network operations or portfolio support. The related brand ecosystem should not be collapsed into one undifferentiated “VC company”. This guide does not treat an old press release about a fund’s size as current deployable capital.
The official IAN portfolio includes Druva, FarEye and WebEngage. Treat those names as starting points for researching different enterprise-software problems, not as evidence that each business is seeking funding or hiring today. A dated portfolio appearance establishes less than a fresh announcement about a particular round; keep the two kinds of evidence separate.
How to shortlist venture capital firms in Delhi NCR
| Question | What to research | Why the answer matters |
|---|---|---|
| Does the company fit? | Current mandate, relevant partner and recent officially described investments | A nearby office does not make an investor suitable for every business. |
| Is the stage appropriate? | Product maturity, customers, revenue quality and the proposed use of funds | A pre-product business and a scaling company need different evidence. |
| Is the funding route clear? | Exact fund, network or vehicle; official submission process | The brand and legal investor may differ. |
| What is the geographic relationship? | Official office details, team biographies and role location | New Delhi, Gurugram and a remote Delhi-linked team are different claims. |
| Is the information current? | Publication date, live team page and direct official confirmation when necessary | Old fund sizes, team members and contact details can persist in directories. |
Build a shortlist with evidence fields rather than collecting the largest possible number of names. Keep a source URL, the date checked and one reason for inclusion. Leave an uncertain field marked “not verified”. A blank is more useful than a fabricated ticket size because it tells you which question still needs an answer.
Researching venture capital firms in Delhi: analyst checks
A useful company note connects the product to its economics. Start with the customer’s problem and the alternative they use today. Define who pays, why they pay and whether repeat usage is visible. Then examine how the business acquires customers, delivers its service and converts revenue into cash. A large market estimate is weak evidence if the company cannot reach customers economically.
For a software business, separate recurring subscription revenue from implementation work and one-off projects. Ask whether customer concentration could make reported growth fragile. For a marketplace, distinguish transaction value from the revenue retained by the platform. For a physical product, account for production, fulfilment, returns and working capital. These questions make the analysis specific to the business instead of repeating a generic “large market, strong team” template.
Worked example: dilution, runway and a weaker downside case
Suppose a fictional startup raises ₹4 crore of primary equity at a ₹16 crore pre-money valuation. Assume no convertible securities, option-pool change or transaction costs. Post-money value is ₹20 crore, and the new investor owns 20%. Existing holders collectively retain 80%. This simplified calculation is a teaching example, not a valuation recommendation.
| Item | Base case | Downside case |
|---|---|---|
| Cash available after the primary raise | ₹4.8 crore, including ₹0.8 crore existing cash | ₹4.8 crore |
| Monthly cash receipts | ₹30 lakh | ₹24 lakh |
| Monthly cash payments | ₹50 lakh | ₹56 lakh |
| Net monthly cash burn | ₹20 lakh | ₹32 lakh |
| Simple runway at unchanged burn | 480 ÷20 =24 months | 480 ÷32 =15 months |
The investment question is not merely whether 24 months sounds comfortable. What milestone can the company reach before it must raise again? Does the downside case leave enough time for that milestone and fundraising? Are cash receipts delayed by customer credit terms? Is the founder’s “revenue” number actually cash collected? Explain those differences before presenting the model.
Now change one assumption: if part of the ₹4 crore transaction is a secondary purchase from existing holders, that part does not add cash to the company. The ownership calculation and the cash-runway calculation must be reconciled separately. Similarly, an option-pool increase can change dilution. The simple 20% result cannot be carried into a more complex capital structure without adjustment.
For model foundations, read what financial modelling involves. For interview practice, use the valuation questions guide and defend each assumption rather than memorising a multiple.
Turn firm research into an application or investment memo
A concise memo can contain a company description, customer evidence, market map, revenue drivers, a small operating model, risks and a clear recommendation for the next research step. Put sources beside the claims. Use a public company or fictional data if you cannot obtain private information legitimately. Do not imply access to management, customers or confidential numbers that you do not have.
For each risk, explain what evidence would change your view. “Competition is intense” is vague. “The model assumes customer acquisition cost falls while two larger competitors are increasing marketing” is a testable concern if you can support those facts. Likewise, distinguish a portfolio company’s success story from evidence about a fund’s realised return. The latter requires a different dataset.
Before applying, check the official careers route or a current employer-posted vacancy. A visible analyst on a team page is not evidence of an available analyst position. Research investment, fund-accounting, portfolio-finance and operating roles separately. They can all sit around a venture organisation but require different work samples. A course certificate can support skill development; it does not establish access to a particular fund.
VC equity, venture debt and angel networks are not interchangeable
A local investor list can mix different sources of capital. A venture-capital equity fund normally invests for ownership. A venture-debt provider lends under a financing agreement. An angel network can connect a company with individual investors and may operate alongside separate funds. Identify the actual vehicle before comparing an offer or describing the organisation in an interview.
This matters when searching for venture capital firms in Delhi NCR. A debt investment does not produce the same ownership calculation as a primary equity round, and a network’s entire membership is not a single investment committee. Ask which legal entity would invest, which instrument it proposes and which team has the relevant mandate.
Venture capital firms in Delhi NCR: compare the investment approach
| Organisation | Evidence to use in your shortlist | Do not assume |
|---|---|---|
| She Capital | Named team, official portfolio and the specific fund identity. Use the team and portfolio to explain why the company may fit. | Every company in a similar sector will be eligible, or that every vehicle has the same terms. |
| Titan Capital | Its team distinguishes seed and early-growth investing. Its official pitch form asks for company stage, amount sought and differentiation. | A field in an application form is a promise of funding at that stage. |
| Leo Capital | Its official positioning is cross-continental early-stage technology investing. Delhi is one of its hubs. | Delhi is its global headquarters or that location alone determines investment fit. |
| growX | Its official description emphasises B2B, early-stage and early-growth investment. Check the current fund and pitch route. | A Delhi street address has been independently verified for this review. |
| Indian Angel Network | Identify whether you mean the network, a particular fund or a portfolio relationship. | All members invest together or portfolio history confirms a current open mandate. |
The growX investment description discusses early and early-growth B2B opportunities, while Leo Capital’s own site explains its technology and international positioning. Read those primary descriptions before copying the sectors or cheque sizes from a directory. Fund size, assets under management and money currently available for new investments are different measures.
How to approach venture capital firms in Delhi with a relevant pitch
The official Titan Capital investment form provides a useful practical checklist. It asks for the founder’s background, company website, a concise description, the problem and why now, sector, stage, amount being raised, prior funding, competitors and differentiation, plus a pitch deck. These are observed form fields, not evidence that a submission will be accepted.
Translate those fields into a short investment case. For a fictional B2B software company, “we sell workflow software to Indian distributors” is clearer than “we are revolutionising commerce.” Explain the user, the problem, what the customer pays and the evidence of demand. Then state the amount sought and the operating milestone it would fund. A clear milestone could be a product release or a measurable sales target; it should not be an unsupported promise.
Use comparable definitions in the deck. Separate recurring revenue from one-off implementation fees, contracted business from realised revenue, and paying customers from free users. If your company is pre-revenue, say so and show the evidence you do have. Hiding a missing metric behind a larger vanity metric weakens the case.
For growX, its official contact page directs funding pitches to a separate pitch portal and distinguishes them from career enquiries. Follow the route published by each firm. Avoid sending a job application through an investment form or treating a generic inbox as a verified partnership contact.
A useful investment memo is more than a firm biography
For an analyst work sample, choose one company and write a two-page memo before building a large model. Cover the customer problem, revenue model, market alternatives, evidence of demand, unit economics, cash runway and the main reason the investment could fail. Put the source and date beside every important input. Label assumptions separately from reported facts.
For instance, a fictional software business with ₹10 lakh monthly recurring revenue and ₹2 lakh monthly customer churn has 20% gross monthly revenue churn before expansion. That is ₹2 lakh divided by the opening ₹10 lakh, not a statement about customer-count churn. If expansion adds ₹1 lakh in the same month, net revenue retention on that opening cohort is 90%, assuming no other changes: (₹10 lakh − ₹2 lakh + ₹1 lakh) ÷ ₹10 lakh. New-customer revenue does not belong in that cohort calculation.
Explain why the metric matters. Strong new sales can hide weak retention, so a revenue-growth chart alone may miss a problem. Equally, a company with longer implementation cycles may need a different analysis from a simple subscription example. Adapt the questions to the actual business rather than forcing every company into a SaaS template.
If you need to practise the forecasting and valuation behind that memo, explore our financial modelling course alongside the worked resources in this article. Model-building is one relevant skill; completing a course does not guarantee a venture-capital role or investment.
Frequently asked questions
Which are the top venture capital firms in Delhi?
A “top” list needs a defined metric and comparable evidence. This guide instead documents the Delhi/NCR connections and research routes for She Capital, Titan, Leo, growX and IAN, with growX geography explicitly unconfirmed. It does not rank investment returns, founder satisfaction or career prospects.
Is Gurugram part of Delhi?
Gurugram is a separate city in Haryana within Delhi NCR. An NCR shortlist may include it, but a New Delhi office claim requires its own evidence. This guide labels the distinction rather than moving firms between cities for the keyword.
Does a large portfolio mean a firm is currently investing?
Not necessarily. A portfolio page records relationships; it may include historical investments and exits. Check the current mandate and official submission route. Neither a large historical fund size nor a long company list proves how much capital is available today.
Should a founder choose the investor nearest to the office?
Location can affect access, but stage, business fit, relevant experience and the proposed terms matter more to the financing decision. Build the case for fit first. An investor’s proximity does not guarantee interest or make the terms suitable.
Venture capital firms in Delhi: building your final shortlist
The strongest shortlist is one you can explain. Know which organisation you mean, its documented location, the relevant team and the evidence of fit. For founders, that produces a more focused funding approach. For candidates, it produces a more credible application and work sample. Keep uncertain facts visible and revisit them before acting; that habit is more valuable than a long directory of unverified names.

A CFA charterholder with hands-on experience across investment analysis and finance education. At MentorMeCareers, he writes and reviews content on CFA, financial modeling, and investment banking careers — grounded in real market data rather than generic advice, and shaped by what actually helps candidates and professionals succeed.