

Last updated on October 24th, 2026 at 09:04 pm

EBITA or Earning before Interest tax and amortisation is often considered the surrogate for a company’s earnings. Yes, you heard it right! Moreover, EBITA can be used in multiple ways along with other line items like Revenue and company valuation to make meaningful judgements about the business quality.

What is EBITDA
EBITDA means earnings before interest, taxes, depreciation and amortisation. It is a non-GAAP financial measure, rather than a required income-statement line item with a fixed position. Check how each company defines and reconciles it before making comparisons.
EBITDA Full Form in Finance
- EBITDA stands for Earnings before interest taxes depreciation and amortization
- EBITA full form stands for Earnings before interest taxes and amoritisation.
What is Amortization in EBITDA?
Amortisation allocates the cost of a finite-lived intangible asset, such as a patent, over its useful life. Depreciation performs a similar allocation for tangible assets. EBITDA adds back both expenses; EBITA adds back amortisation but leaves depreciation deducted.
EBITDA Meaning
You all are aware that the three financial statments include
- Income Statement- Measures profitability during a period
- Balance sheet- shows the position of assets & liabilities at a point
- Cash flow statement- Reconciles the cash inflow and outflow to understand the ability to generate cash.
EBITA measures earnings before interest, taxes and amortisation. It differs from EBITDA because depreciation remains an expense in EBITA.
EBITDA Example
So, one of the darling stocks of long term investors in India. This company is an example of a model company for financial analysis.
The illustration below shows operating profit. Do not automatically treat an operating-profit figure as EBITDA: first check whether depreciation and amortisation have already been deducted. Higher EBITDA alone does not establish market dominance; compare margins, cash generation and business risks as well.

EBITDA Formula
Simply put at a very broad top view level, EBITDA calculation formula is;
- EBITDA = EBIT + Depreciation + Amortisation
- What is Direct cost?
Here you need to understand that direct cost includes, costs which are directly attributed to the revenue. For example; In case of TITAN company the direct cost is Raw gold, because 80% of their revenue comes from jewelery business.
- What is Indirect Cost
Now , indirect costs include costs which are attributable to selling, managing, branding etc which although are necessary to generate revenue. But they do not include in the cost of the product.
The corresponding EBITA formula is EBITA = EBIT + Amortisation. Therefore, EBITDA = EBITA + Depreciation, using the same earnings basis and period.
EBITDA = Revenue − operating costs excluding depreciation and amortisation. Include all relevant operating costs, not just salaries and marketing, and check the company’s reconciliation for any further adjustments.
What is EBITA In Business
So when I operate my own business, this is how the thinking goes.
- Salary cost is around 40%
- Marketing at around 15%
- IT expenses at around 5%
These three expense categories total 60% of revenue, leaving 40% before any other costs. This is not enough information to calculate EBITA or EBITDA margin: other operating expenses and the treatment of depreciation and amortisation must also be known. Appropriate margins vary by industry and business model.
EBITDA can help analyse profitability, but it is not operating cash flow. An indirect cash-flow reconciliation starts from profit and adjusts for non-cash items and working-capital movements, with interest and tax treatment depending on the reporting framework.
- Operating cash flow requires a full reconciliation of profit, non-cash adjustments and working-capital movements.
EBITDA omits working-capital movements and does not deduct capital expenditure. Review the cash-flow statement separately when assessing cash generation and debt repayment capacity.
Understanding EBITA in Context with Net Income, Interest, Taxes, and Amortization
EBITA stands for earnings before interest, taxes and amortisation. Depreciation remains deducted in EBITA, whereas EBITDA adds it back. In a simplified example with no other reconciling items, net income of $1,000,000 plus interest expense of $100,000, income tax expense of $150,000 and amortisation of $50,000 gives EBITA of $1,300,000. If depreciation is $100,000, EBITDA is $1,400,000. Check the company’s definitions and any non-operating items before comparing these measures.
EBITDA Case Study: Lead Prices & Battery Manufacturers
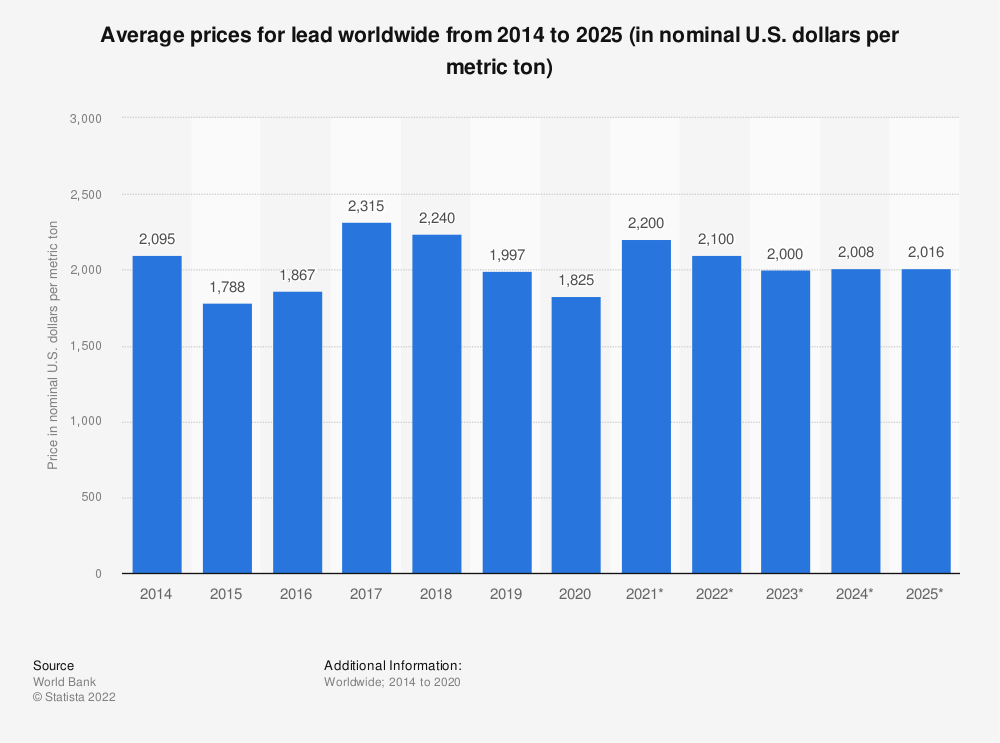
This historical illustration shows how input costs can affect margins. In battery manufacturing, lead is an important raw material; the charts below are historical examples, not current market data.
Prices of lead since 2014
Now, imagine a company like Exide industries, which manufactures lead batteries for cars.
However, If their margins are not good, such price fluctuations can lead to tremendous business shocks or even shutdowns.
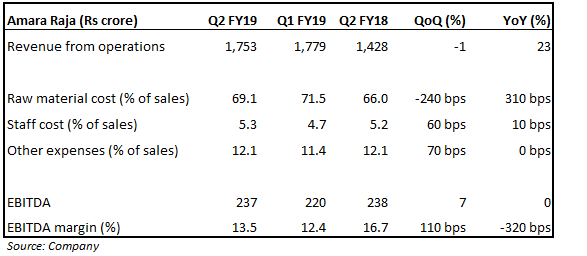
Amaraja Battery EBITDA Margins
Comparing EBITDA Margins Across Industries
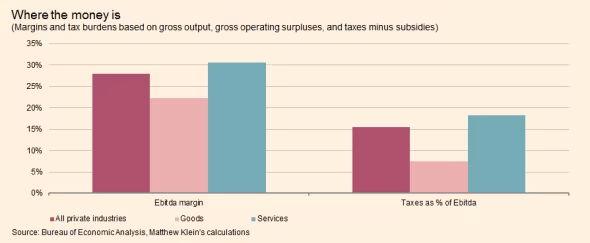
The illustrations show that EBITDA margins can differ substantially across industries. Compare companies with similar business models and accounting definitions.
Also, You may ask why? Well, because a service industry like Information technology has no cost of goods but the cost of service.
Whereas a manufacturing industry will have costs of goods plus salaries to pay. Now,I came across this very nice image, which shows margins across various industries
source: FT Times
The historical industry chart should not be read as a current or universal 90% EBITDA margin for real estate. Check the underlying sample, period and definition before drawing conclusions.
EBITA CALCULATION EXAMPLE
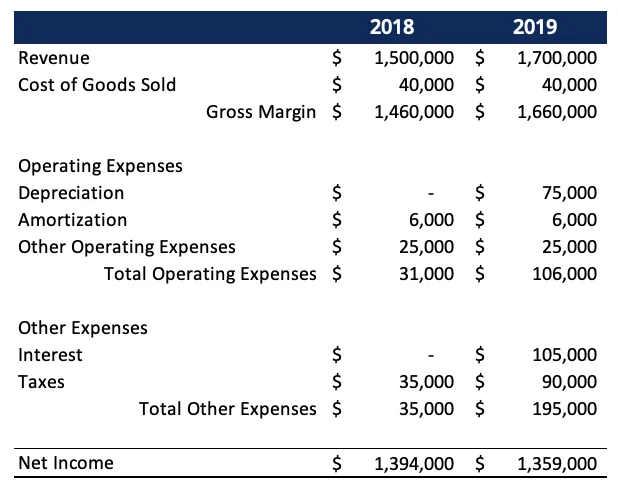
For example;In 2018, the company had total revenue of $1,500,000 and a net income of $1,394,000. In 2019, total revenue increased to $1,700,000 and the net income fell to $1,359,000. Higher sales with smaller profits can be explained using EBITA. When the company’s net income is adjusted for taxes, interest, and amortization expenses, the profit instead increases.
EBITA for 2018 = $1,394,000 + $6,000 + $35,000 + $0 = $1,435,000
EBITA for 2019 = $1,359,000 + $6,000 + $90,000 + $105,000 = $1,560,000
Now, The above calculation shows that even though the company’s net income decreased by $35,000, the earnings before interest taxes and amortization for the company increased by $125,000 in 2019.
Waste management Inc- Case study
So, i came accross this very interesting case study done by Moody’s on waste management Inc which is a market leader waster service industry.
- This business was high on cash requirement ( high capex and opex intensive industry)
- Due to this, its obvious that the company will have low free cash for debt reduction.
- Now during a 21 months analysis(1998-1999), it was found that waste management Inc. EBITDA was robust but not cashflow.
- Infact in 1999, EBITDA was $4 billion, however on closer analysis. The net cash from operatinng activities was only $1.5 Billion. While the company spent $4.6 billion on capex. Leading the company to borrow $2 billion to manage the shortfall.
So, the conclusion is that EBITDA is good measure of company’s profitability. However, a very dangerous financial metric to determine a company’s actual cash profits.
5 Limitations of EBITA
Now let me quickly summarise the marjor challenges with blindly following this financial metric.
- Ignores working capital changes
Working-capital movements can reduce operating cash flow even when EBITDA remains strong. For example, sales recorded on credit may increase earnings before the customer pays. These cash-flow movements do not automatically reduce accrual-based EBITDA.
- Misleading Liquidity Picture of a company
EBITDA ÷ (interest + principal repayments) is an EBITDA-based debt-service coverage measure, not the standard interest coverage ratio. Interest coverage is commonly EBIT ÷ interest expense. Neither measure replaces an assessment of cash available for debt service.
- Ignores Capex
When I was analysing GAIL, a couple of years back. I was very with the operation cash flow, however the size and scale of capital expenditires was significant. So significat that most likely the company would always be in the borrowing mode.
- Misses Earnings Quality
Quality of earnings depends on how closely does your revenue and profit match with cash earnings. Lower the difference, the bettter the quality.
- Vulnerability to Accounting Manipulation
Since you and me as an investor are anyways fascinated by EBITDA margins. So its quite likely that the company also will try to make sure they paint a rozy picture.
5 Uses of EBITDA
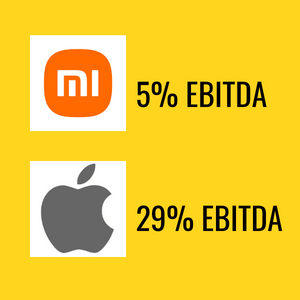
Now, let’s discuss ways in which EBITDA can support analysis, alongside cash flow and other financial measures.
- Firstly to Filtering Companies: Calculate EBITDA/ Revenue to filter out profitable companies or decide on which business to enter.
- Compare business economics: Margins can reflect pricing, costs and product mix, but do not prove product quality by themselves.
- Thirdly, to Increase Efficiency: A company could analyse its costs to understand where the leakages are and fix them.
- Also, an indication of an Increase in Capital Expenditure: A company could find ways to spend money on machines and automation, which could reduce operational expenses and increase EBITDA margins
- Finally, Work on Scale: Generally, margins are lower initially in a business because the sales haven’t taken off, but sometimes, this can also be due to the product not being scalable at all. Which would mean that company cuts its losses on unscalable business or products and work on scalable ones.
Conclusion
I would suggest playing around with company data and understanding how different business work with different margins. Also, understand that EBITDA margins don’t necessarily mean cash. A company could have great EBITDA Margins with products sold on credit. Then what? All noise but no real cash.
Frequently Asked Questions
How is EBITA Calculated?
There are two methods by which one can calculate the EBITA.
- Direct Method:
For a simplified operating calculation, subtract all operating costs, including depreciation but excluding amortisation, from revenue. If amortisation is embedded in COGS or other operating costs, add it back once; do not assume it appears only in operating expenses.
EBITA = EBIT + Amortisation, using a consistently defined EBIT figure.
- Indirect Method:
A simplified net-income bridge adds back interest expense, income tax expense and amortisation. Review net interest, non-operating items and the company’s reconciliation before applying it to reported figures.
EBITA = Net income + Interest + Taxes + Amortization
Also, Companies may not provide a breakdown of operating expenses of the cost of goods sold. In such scenarios, the indirect method can be used to calculate the company’s EBITA.
What is the difference between EBITDA and EBITA?
EBITA adds back amortisation while leaving depreciation deducted. EBITDA adds back both depreciation and amortisation. On the same earnings basis, EBITDA = EBITA + Depreciation.
Related Articles

A CFA charterholder with hands-on experience across investment analysis and finance education. At MentorMeCareers, he writes and reviews content on CFA, financial modeling, and investment banking careers — grounded in real market data rather than generic advice, and shaped by what actually helps candidates and professionals succeed.