Last updated on October 24th, 2026 at 09:04 pm
You are free to use this image on your site, template etc. Just provide us the attribution link
What is Prepaid Expense?
Prepaid expenses represent expenditures that have been paid for in advance but not yet recorded as expenses. These are listed as assets on the balance sheet because they provide future economic benefits to the company. Common examples include prepaid rent and prepaid insurance.
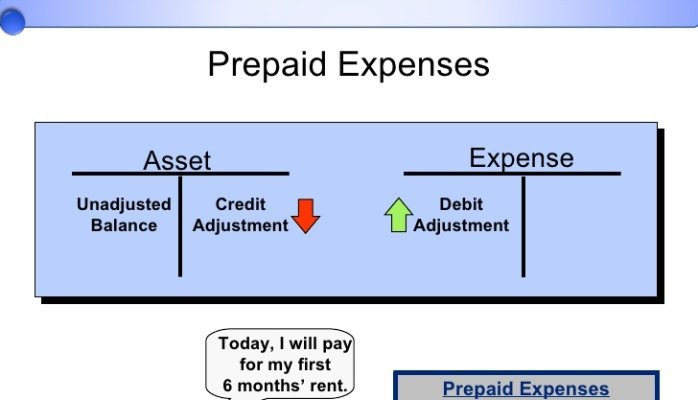
Prepaid expenses entry
So, Prepaid expenses entry, represent expenditures that have not been recorded by a company as an expense but have been paid for in advance. While, a prepaid expense is a type of asset on the balance sheet For you that results from a business making advanced payment for the provided goods and services that you would be receive in the future.
A payment for future benefits is initially recorded as a prepaid asset. As those benefits are consumed, the cost is recognised as an expense in the income statement and the prepaid asset on the balance sheet decreases.
Also, the Pre Paid expenses you always shown in the asset side, because the other party who we have paid in advance is liable to provide us the service in the future. Hence its liability for the other party and asset for us
Types of Pre-Paid Expenses
| types of Prepaid Expense | Description | Example |
| Prepaid Rent | Payment made in advance for future rent periods. | A company pays a year’s worth of rent upfront to secure a favorable rate. |
| Prepaid Insurance | Upfront payment for insurance coverage over a specified period. | A car owner pays the full year’s premium at the beginning of the policy term. |
| Prepaid Subscriptions | Lump sum payment made in advance for services like magazines, newspapers, or streaming platforms. | Subscribing to a yearly magazine ensures regular issues without monthly payments. |
| Prepaid Maintenance | Upfront payment for maintenance contracts or service agreements. | A manufacturing plant pre-pays for equipment servicing throughout the year. |
| Prepaid Advertising | Upfront payment for advertising campaigns and media placement. | A company pre-pays for TV commercials or digital ads to run over a specific period. |
Meaning of Prepaid Expenses Journal Entry
Under accrual accounting, a payment for future insurance coverage is initially recognised as a prepaid asset. The cost is then recognised as an expense over the coverage period as the benefit is consumed.
Example
For example, an annual insurance premium paid before coverage begins provides benefits over twelve months. Recognising the entire payment as an expense immediately would not reflect that pattern. Record the unexpired coverage as a prepaid asset and allocate the cost over the coverage period.
Prepayments arise when a business pays before receiving the related goods or services. For insurance paid in advance, only the unexpired coverage remains a prepaid asset; coverage already consumed is an expense.
Journal Entry for Prepaid Expenses: Detailed Overview
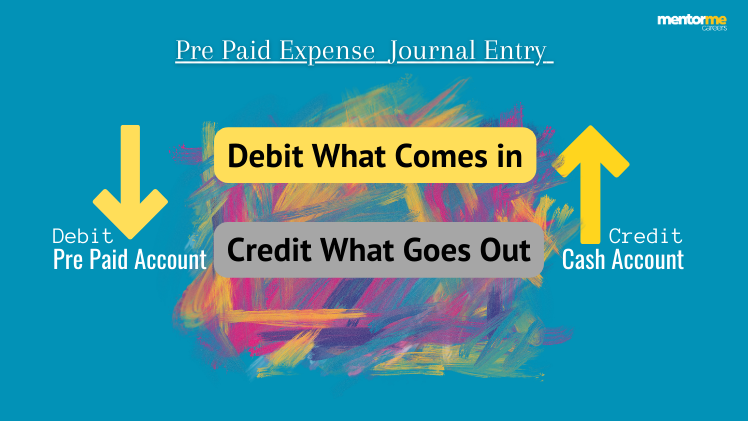
When recording the journal entry for prepaid expenses, it’s essential to recognize that these entries involve both the initial payment and subsequent adjustments. Initially, the prepaid expense is recorded as an asset, which reflects a future economic benefit for the company. The entry for prepaid expenses is made by debiting the prepaid expense account and crediting the cash account, indicating that payment has been made upfront. Over time, as the benefit of the prepaid expense is realized, it is gradually expensed. This means that the expense is spread out, aligning with the period in which it provides benefits. The adjusting journal entries reflect this allocation, ensuring that expenses are recognized in the correct accounting periods. For instance, a prepaid rent payment recorded as an asset is expensed monthly to match the benefit received during each month.
Prepaid Expenses Accounting: Detailed Insight
Prepaid expenses accounting involves recognizing and allocating expenses over the period they provide benefits. Companies must debit the prepaid expense account when making an upfront payment. This approach ensures that expenses are matched with the revenues they help generate, adhering to the matching principle. Journal entries for prepaid expenses are crucial in maintaining accurate financial records, impacting both the balance sheet and the income statement.
Recognizing Expenses Over Time: Accounting for Prepaid Items
Expenses over time need to be managed carefully to ensure accurate financial reporting. For prepaid items, such as insurance or rent, the cost is initially recorded as an asset. This approach ensures that the expense is recognized progressively throughout the benefit period. As time passes, the prepaid expense is systematically transferred from the asset account to the expense account through adjusting journal entries. This method aligns the cost with the periods that benefit from the payment, adhering to the matching principle. For example, if a company pays $12,000 for a one-year insurance policy, it will record $1,000 each month as an expense, reflecting the insurance coverage used in that month and maintaining accurate financial statements.
Prepaid rent journal entry
Assume a business pays 5,000 on 31 March 2021 for rent covering April to June. The initial payment is recorded as follows:
| Date | Account | Debit | Credit |
| 31/03/2021 | Pre Paid Rent | 5000 | |
| 31/03/2021 | Cash | 5000 |
At 30 June 2021, the full quarter’s rent has been consumed. The following summarises the quarter’s expense recognition. If preparing monthly accounts, allocate the expense across April, May and June rather than waiting until quarter-end.
| Date | Account | Debit | Credit |
| 30/06/2021 | Rent Expense | 5000 | |
| 30/06/2021 | Pre Paid Rent | 5000 |
Prepaid Insurance Journal Entry
Assume a business pays 24,000 on 1 April 2021 for twelve months of insurance coverage beginning that day. On payment, debit Prepaid Insurance and credit Cash for 24,000. After one month, recognise insurance expense of 2,000 by debiting Insurance Expense and crediting Prepaid Insurance. The remaining prepaid asset is 22,000.
| Date | Account | Debit | Credit |
| 01/04/2021 | Prepaid Insurance | 24000 | |
| 01/04/2021 | Cash | 24000 | |
| 30/04/2021 | Insurance Expense | 2000 | |
| 30/04/2021 | Prepaid Insurance | 2000 |
Effect of Prepaid Expenses on Financial Statements
The initial payment changes the composition of assets: cash decreases and the prepaid asset increases by the same amount. Total assets are unchanged at that point, and no expense is recognised for benefits not yet consumed. The payment is still a cash outflow. As benefits are consumed, debit the relevant expense and credit the prepaid asset; this reduces profit and the prepaid balance without another cash payment. For example, 120,000 paid for twelve months of warehouse rent produces a monthly rent expense of 10,000 in the income statement, while the unexpired amount remains an asset on the balance sheet.
Prepaid expenses in the balance sheet
Firstly, let’s Assume a company ABC purchases insurance premium for the upcoming 12-month period and pays $180,000 upfront for it. So, ABC Company will initially book the full $180,000 as a debit to prepaid insurance, an asset on the balance sheet, and a credit to cash. Also, Each month, you would make an adjusting entry to expense $15,000 (1/12 of the prepaid amount) to the income statement through a credit to prepaid insurance and a debit to insurance expense. Finally, In the 12th month, the final $15,000 will be fully expensed and the prepaid account will be zero.
Frequently Asked Questions on Prepaid Expenses Journal Entry?
What are the advantages of Pre paid expenses?
Prepaid expenses offer several key advantages. They enable better budgeting and expense management by allowing businesses to pay for future services or goods at current prices. This shields them from potential price increases. Prepayments can also improve cash flow management, as upfront payments might come with discounts or favorable terms. Additionally, they streamline accounting by simplifying expense recognition over time, reducing monthly fluctuations. Businesses can leverage prepaid expenses to enhance financial stability, negotiate better terms with suppliers, and allocate resources more efficiently. Overall, prepaid expenses contribute to smoother operations, cost savings, and improved financial planning in various industries.
Are prepaid insurance a current assets?
Prepaid insurance is generally a current asset to the extent that the coverage will be consumed within the normal operating cycle or twelve months. Any portion covering a longer period may be classified as non-current. As coverage is consumed, recognise insurance expense in the income statement and reduce the prepaid asset.
What are some examples of Pre Paid Insurance?
Here are some examples of prepaid insurance:
- Auto Insurance: A company pays its annual auto insurance premium in advance. The unexpired portion of the premium is recorded as a prepaid insurance asset; coverage already consumed is recognised as expense.
- Property Insurance: A business pays for property insurance coverage for the next six months at the beginning of the year. The amount paid in advance is recorded as a prepaid insurance asset on the balance sheet.
- Health Insurance: An employer pre-pays health insurance premiums for its employees for the upcoming quarter. The prepaid portion is considered an asset until the coverage period is reached.
- Liability Insurance: A company pays for liability insurance coverage for the year ahead. Only the unexpired coverage is recognised as a prepaid insurance asset.
- Travel Insurance: A travel agency buys travel insurance to cover its tour packages for the next six months. The unutilized portion is classified as prepaid insurance.
- Professional Liability Insurance: A consulting firm pays for professional liability insurance for the next twelve months. The unexpired coverage is a prepaid asset; the consumed portion is recognised as insurance expense.
Is prepaid insurance a debit or credit?
In accounting, prepaid insurance is initially recorded as a debit to the “Prepaid Insurance” asset account and a credit to the “Cash” or “Bank” account. This reflects the fact that the company has made a payment in advance for insurance coverage, which increases the prepaid insurance asset but decreases the cash or bank balance.
As the insurance coverage is consumed over time, the prepaid insurance asset is gradually reduced, and an expense is recognized. This is done by debiting the “Insurance Expense” account and crediting the “Prepaid Insurance” asset account. The goal is to match the expense with the period in which the insurance coverage is being utilized.