
Last updated on October 5th, 2026 at 05:56 pm
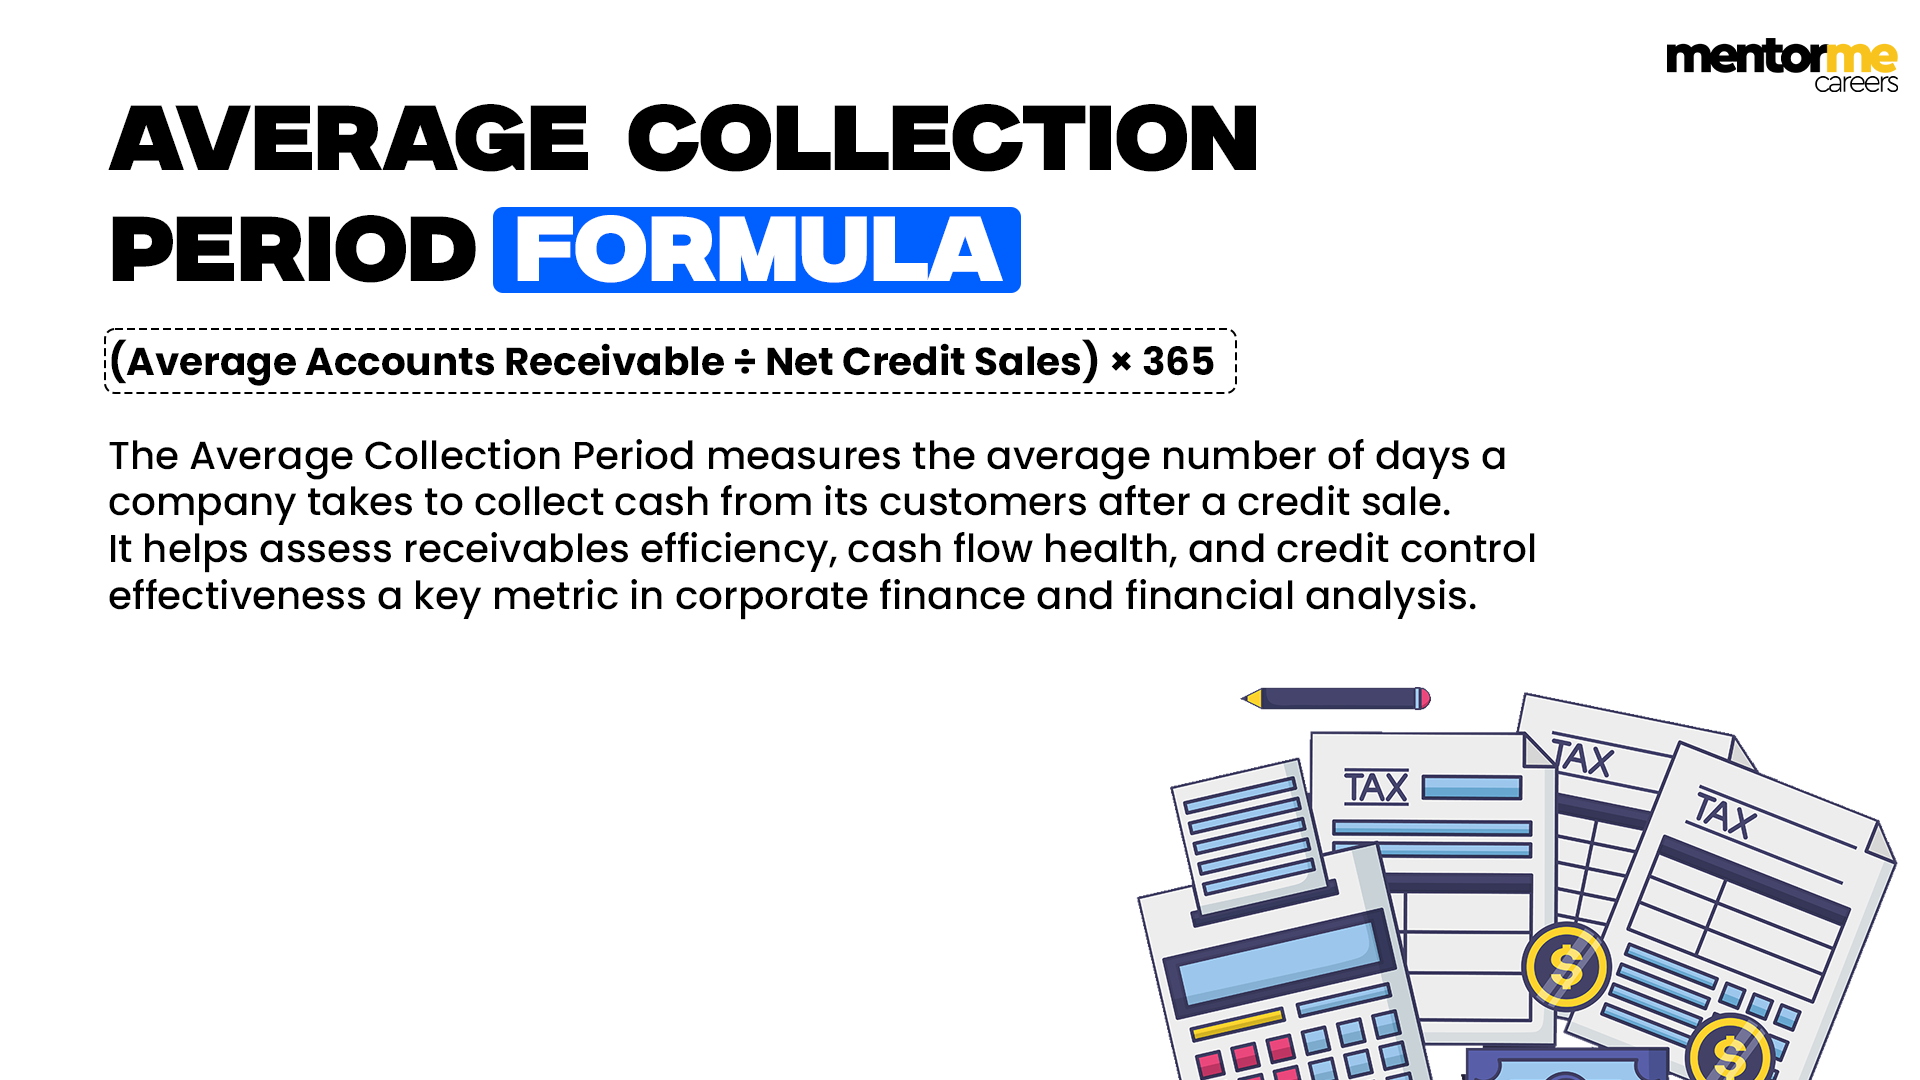
The average collection period (ACP) tells you how many days a company takes, on average, to collect cash from customers after a credit sale. The average collection period formula is:
Average Collection Period = (Average Accounts Receivable ÷ Net Credit Sales) × 365
A lower number means cash comes in faster. I teach this ratio in CFA Level 1 Financial Statement Analysis, where it appears as days of sales outstanding (DSO). It is one of the first numbers an analyst checks to judge how well a company manages its working capital.
| Key takeaways ACP = (Average Accounts Receivable ÷ Net Credit Sales) × 365.The shortcut is ACP = 365 ÷ Receivables Turnover.Judge the result against the company’s credit terms, its own history and its industry. No universal benchmark exists.A rising ACP is an early warning of weak collections or aggressive revenue booking.ACP, debtor days and DSO all describe the same idea. |
What is the average collection period?
When a company sells on credit, it records the sale today and collects the cash later. Until the customer pays, the amount sits on the balance sheet as accounts receivable. The average collection period converts that balance into days. It answers one question: how long does an invoice stay unpaid, on average?
Here is the idea in plain words. If a company has an ACP of 45 days, a sale made on 1 April turns into cash around the middle of May.
You will also see this ratio called debtor days, the debtors’ collection period or days sales outstanding. The inputs come straight from the financial statements: receivables from the balance sheet and sales from the income statement.
Importance of the average collection period
- Liquidity. A company pays salaries, suppliers and lenders in cash, not in sales. The longer customers take to pay, the more cash the business must find elsewhere. ACP therefore sits alongside the liquidity ratios in any analysis.
- Working capital. Receivables are money lent to customers free of interest. A longer ACP ties up more capital and stretches the working capital cycle.
- Credit quality. The older a receivable gets, the more likely it is to become a bad debt.
- Earnings quality. If sales are growing but ACP is growing faster, ask whether the company is booking sales that customers are slow to pay for.
Average collection period formula
ACP = (Average Accounts Receivable ÷ Net Credit Sales) × 365
- Average accounts receivable = (Opening receivables + Closing receivables) ÷ 2
- Net credit sales = Credit sales − Sales returns − Discounts and allowances
- 365 = days in the period. Use 90 for a quarter or 30 for a month. Some textbooks and banks use 360 days, so follow what your exam or employer specifies.
Alternate formula using receivables turnover
ACP = 365 ÷ Receivables Turnover Ratio
Here, receivables turnover = Net credit sales ÷ Average accounts receivable. The two ratios carry the same information. Turnover tells you how many times a year the company collects its receivables. ACP tells you how many days each round takes.
How to calculate the average collection period step by step
- Find the average accounts receivable. Add the opening and closing balances and divide by two. This smooths out swings during the year.
- Find net credit sales. Take credit sales and subtract returns, discounts and allowances. If the company does not disclose credit sales, analysts use total revenue. That understates the true ACP whenever part of the sales is in cash.
- Divide and multiply. Divide average receivables by net credit sales, then multiply by 365.
- Interpret the result. Compare it with the company’s credit terms, with earlier years and with competitors.
The formula in Excel
Put opening receivables in B2, closing receivables in B3 and net credit sales in B4. Then enter: =AVERAGE(B2,B3)/B4*365
Average collection period examples
Example 1: exam-style calculation
A company reports opening receivables of ₹4,00,000, closing receivables of ₹6,00,000 and net credit sales of ₹36,50,000 for the year.
- Average receivables = (4,00,000 + 6,00,000) ÷ 2 = ₹5,00,000
- ACP = (5,00,000 ÷ 36,50,000) × 365 = 50 days
The company takes 50 days, on average, to collect cash from its customers.
Example 2: using receivables turnover
A company has a receivables turnover ratio of 8 times.
- ACP = 365 ÷ 8 = 45.6, or about 46 days
Example 3: reading the result against credit terms
A company gives its customers 30 days to pay. Its ACP works out to 55 days.
Customers are paying 25 days late on average. Either credit control is weak, or a few large customers are stretching their payments. The company is financing 25 extra days of sales out of its own pocket. It should review credit limits, chase overdue invoices and check whether any balance needs a provision for doubtful debts.
Example 4: forecasting receivables in a financial model
Analysts also run the formula in reverse. Suppose you forecast revenue of ₹48,00,000 for next year and assume that the ACP stays at 50 days.
- Forecast receivables = 48,00,000 × 50 ÷ 365 = ₹6,57,534
This is how receivables are projected on the balance sheet of a financial model. We teach the full method in our financial modelling course with placement.
Interpretation of the average collection period
What a low collection period indicates
Customers pay quickly, credit control is tight and cash is available for operations. One caution: a very low ACP can mean credit terms so strict that the company loses customers to competitors who allow more time.
What a high collection period indicates
Collections are slow. The cause may be lenient credit terms, weak follow-up, billing disputes or customers in financial trouble. Cash stays locked in receivables, and the company may need to borrow to pay its own bills.
Is there a good average collection period?
No single number is good for every business. A grocery chain collects almost at once. An engineering contractor may wait months for payment. Use these three comparisons instead.
| Compare ACP with | What it tells you |
| The company’s credit terms | An ACP close to the terms means customers pay on time. An ACP well above the terms means collections are slipping. |
| The company’s own past | A steady rise over several years is a warning, even if the level still looks acceptable. |
| Industry peers | This shows whether the company is stricter or more lenient than its competitors. |
Average collection period vs receivables turnover
| Basis | Average collection period | Receivables turnover ratio |
| What it measures | Days taken to collect cash from credit customers | Number of times receivables are collected in a period |
| Unit | Days | Times |
| Formula | (Average receivables ÷ Net credit sales) × 365 | Net credit sales ÷ Average receivables |
| Better when | Lower | Higher |
| Link | ACP = 365 ÷ Turnover | Turnover = 365 ÷ ACP |
Limitations of the average collection period
- Seasonality. A year-end balance may not represent the whole year. Use monthly or quarterly averages when you have them.
- Missing credit sales. Most annual reports do not disclose credit sales. Using total sales makes ACP look better than it is.
- Averages hide the spread. One large slow payer can sit behind a healthy-looking number. An ageing schedule of receivables shows what the average hides.
- Year-end window dressing. A company can push collections before the balance sheet date, or sell its receivables, to report a lower figure.
- Different conventions. Some companies use 360 days and others use closing balances, so compare like with like.
Average collection period for exams and interviews
How to explain it in one line
“The average collection period measures the average number of days a company takes to collect cash from its credit customers.”
Why interviewers ask about this ratio
It tests whether you understand working capital, and whether you can connect the income statement, the balance sheet and cash flow in one answer.
Common follow-up questions
- What happens if ACP rises year on year? The company collects cash more slowly. Cash flow from operations falls behind profit, and the risk of bad debts rises.
- Is a lower ACP always better? No. Very strict credit terms can cost the company sales.
- How does ACP link to the cash conversion cycle? The cycle equals days of inventory plus days of receivables minus days of payables. ACP is the middle term.
- What is the difference between ACP and DSO? They are the same concept. DSO is often calculated on closing receivables and for a quarter.
For more practice, work through these ratio analysis problems with solutions and financial market questions and answers. Ratios such as this one form a core part of our CFA Level 1 course.
Conclusion
The average collection period turns a balance sheet number into something you can picture: the number of days that cash stays stuck with customers. Calculate it with average receivables and net credit sales, read it against credit terms, history and peers, and watch the trend more than the level. A company that collects faster needs less borrowed money to grow.
FAQ
What is a good average collection period?
It depends on the industry and on the credit terms the company offers. An ACP close to the stated credit period is healthy. An ACP that is well above it, or that rises every year, needs investigation.
Is the average collection period the same as DSO?
Yes, in concept. Both measure the days taken to collect receivables. DSO is often calculated on closing receivables and for shorter periods, so the two figures can differ slightly.
Can the average collection period be negative?
No. Receivables and sales are both positive numbers, so a negative result points to an error in the data.
Why is the average collection period high?
The usual causes are loose credit terms, weak follow-up on overdue invoices, billing disputes, slow-paying large customers and delayed invoicing.
How can a company reduce its collection period?
It can invoice faster, check customers’ credit before selling, offer discounts for early payment, follow up on overdue invoices regularly and tighten terms for habitual late payers.
Should I use 360 or 365 days in the formula?
Use 365 unless your exam, textbook or employer specifies 360. Whichever you choose, use the same figure every time so that your comparisons stay valid.
Related articles
| About the author Allen Aravindan, CFA is a CFA charterholder and the founder of MentorMe Careers, a finance training and placement institute with centres in Pune and Mumbai. He teaches CFA Level 1 Financial Statement Analysis. |

A CFA charterholder with hands-on experience across investment analysis and finance education. At MentorMeCareers, he writes and reviews content on CFA, financial modeling, and investment banking careers — grounded in real market data rather than generic advice, and shaped by what actually helps candidates and professionals succeed.