
Last updated on November 4th, 2026 at 11:41 am

A call date is a date on which a bond’s terms permit the issuer to redeem it before maturity. The first call date is the earliest permitted date under the relevant provision. The issuer does not automatically redeem a callable bond on that date: the issuer’s rights, notice requirements and redemption price come from the bond documents.
Call date vs maturity date
| Term | Meaning | What to verify |
|---|---|---|
| Maturity date | Scheduled date for final principal repayment | Payment amount and remaining contractual cash flows |
| First call date | Earliest date permitted under a particular call provision | Any protection period and exceptions |
| Call price | Amount paid for early redemption under the provision | Par, premium or a formula; treatment of interest |
| Notice date | Date notice is given | Required notice period and communication method |
An issuer may have call rights on specified dates, throughout a period or under a special provision. A make-whole call can use a formula rather than a fixed redemption amount. Therefore, one date in a data feed is not a complete description of the call schedule.
Why an issuer might call a bond
If borrowing costs fall, an issuer may be able to refinance expensive debt with cheaper funding. However, it must consider the call premium, transaction costs, contractual restrictions and its ability to obtain replacement funding. Falling market rates do not guarantee that a particular bond will be called.
The investor faces a different problem. A high coupon may stop earlier than expected, leaving proceeds to reinvest at a lower available yield. Callability can also constrain the bond’s price upside. These are additional risks; they do not remove credit, liquidity or market risk.
The SEC’s Investor.gov explanation describes early redemption and reinvestment risk. It does not suggest that all bonds are callable or that government bonds should be assumed to have the same provisions as corporate debt.
Worked example: cash flows at an early call
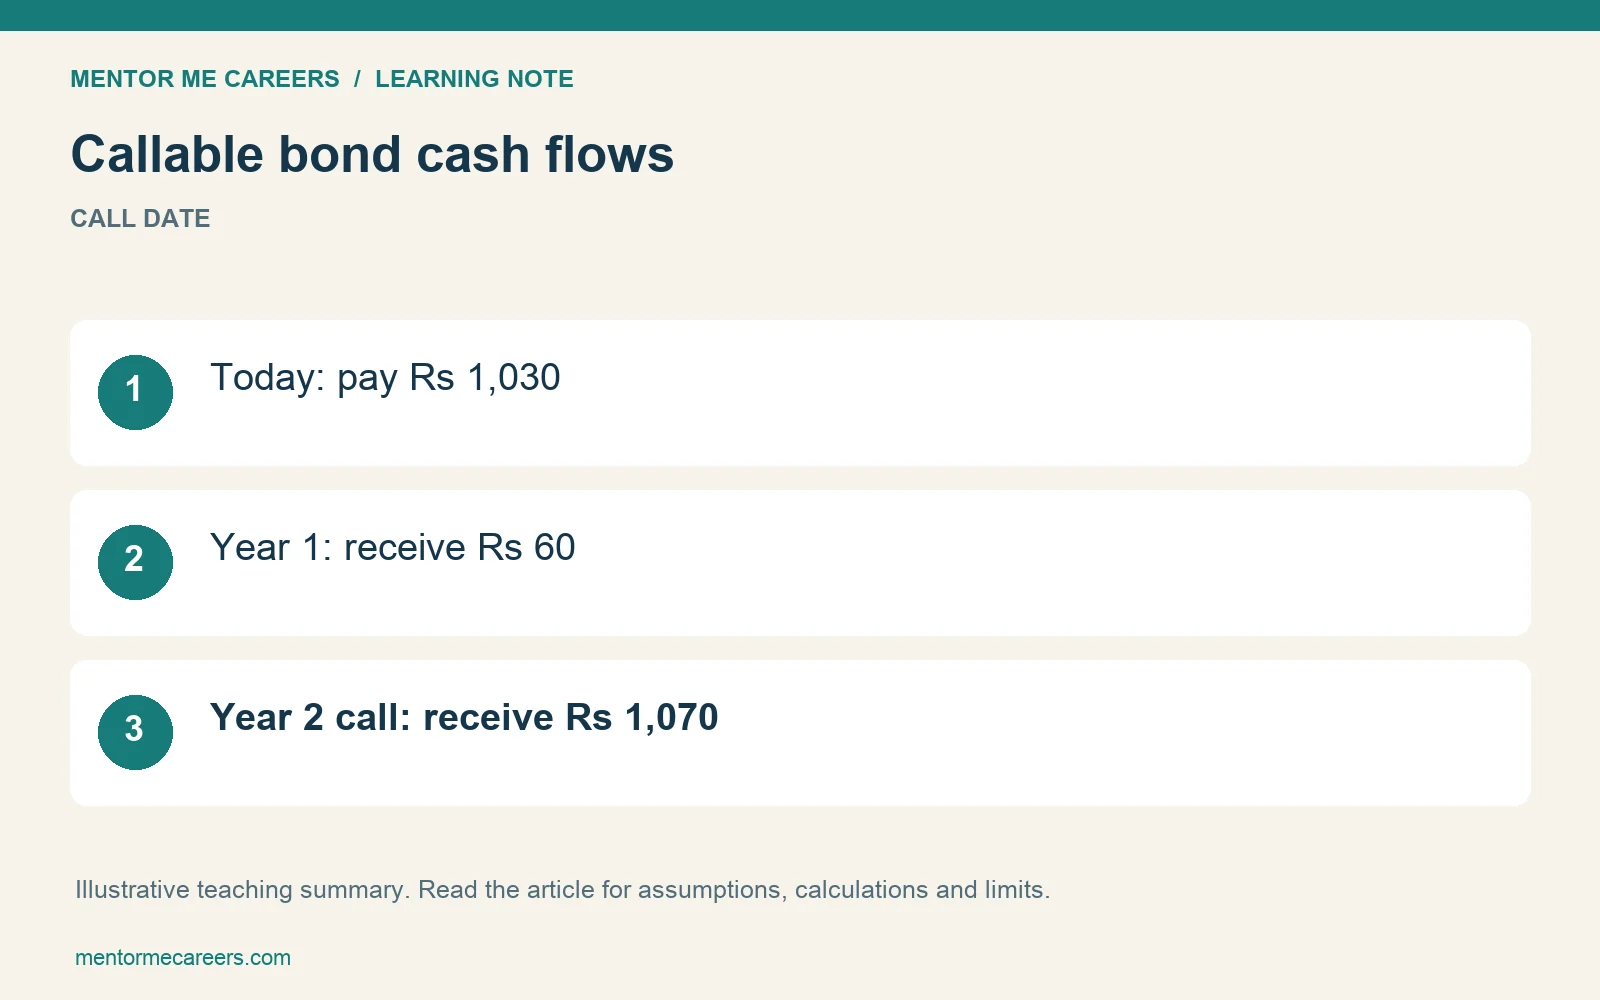
Assume a fictional bond has ₹1,000 face value, a 6% annual coupon and five years to maturity. You pay ₹1,030 on a coupon date, so this simplified example has no accrued interest. The issuer may call it at ₹1,010 in two years, immediately after the second annual coupon.
If the issuer exercises that right, you receive ₹60 after year one and ₹1,070 after year two: the second ₹60 coupon plus ₹1,010 principal redemption. You do not receive the remaining three years of coupons. Your ₹1,030 purchase price is also higher than the ₹1,010 call price.
| Scenario | Year 1 | Year 2 | Years 3–4 | Year 5 |
|---|---|---|---|---|
| Called in year 2 | ₹60 | ₹1,070 | None | None |
| Held to stated maturity | ₹60 | ₹60 | ₹60 each year | ₹1,060 |
Yield to call is the discount rate that equates the purchase price with the assumed call cash flows. For this example, solve 1,030 = 60/(1+r) + 1,070/(1+r)². The annual yield to call is approximately 4.88%. Solving the five-year maturity cash flows gives a yield to maturity of approximately 5.30%.
These are scenario yields, not promises. They assume payments occur as specified and ignore taxes and transaction costs. We use annual cash flows to make the arithmetic clear; real bonds may use different coupon frequencies and conventions.
Coupon rate, current yield and yield to call
The coupon rate is 6% of face value in the example. Current yield is ₹60 ÷ ₹1,030, or about 5.83%. It ignores the loss between purchase price and redemption value, as well as the timing of principal repayment. That is why it differs from yield to call.
Yield to maturity assumes the specified maturity cash flows. By contrast, yield to call assumes a particular permitted early redemption. A yield-to-worst calculation compares relevant contractual redemption scenarios under the calculation convention; it is not a worst-case measure that includes default.
When several call dates or prices exist, calculate the relevant alternatives. Do not assume the first call necessarily produces the lowest yield. For a spreadsheet exercise, enter each dated cash flow consistently and distinguish periodic RATE/IRR calculations from date-based XIRR.
Checks before interpreting a call date
Read the prospectus or final terms, call schedule and any actual redemption notice. Check the bond identifier, currency, settlement date, accrued interest and whether a quoted price is clean or dirty. For a partial call, also check allocation rules; the issuer may not redeem every holder’s full position.
Then test a call and no-call scenario. If your analysis relies on income continuing for five years, an early redemption should be visible in the model. This is a cash-flow modelling issue as well as a definition to remember.
For related practice, see our capital market interview questions and the distinction between funding instruments in our capital injection guide. Educational examples explain mechanics; they do not identify a suitable bond for an individual investor.
Frequently asked questions
Is a call date the same as maturity?
No. Maturity is the scheduled final repayment date. A call date relates to a permitted earlier redemption under the bond terms.
Must the issuer redeem on the first call date?
Not necessarily. An optional call gives a right, not an automatic obligation. Read the actual provision and any notice.
Do I lose all interest if an issuer calls a bond?
No. Payments follow the terms, including any applicable accrued interest. Future coupons after redemption stop; the exact redemption cash flow must be checked.
Sources and further reading
Reviewed 3 November 2026. Worked cases are fictional teaching examples unless a named primary source is given.

A CFA charterholder with hands-on experience across investment analysis and finance education. At MentorMeCareers, he writes and reviews content on CFA, financial modeling, and investment banking careers — grounded in real market data rather than generic advice, and shaped by what actually helps candidates and professionals succeed.